|
|
|
Economic update · week of August 31
|
|
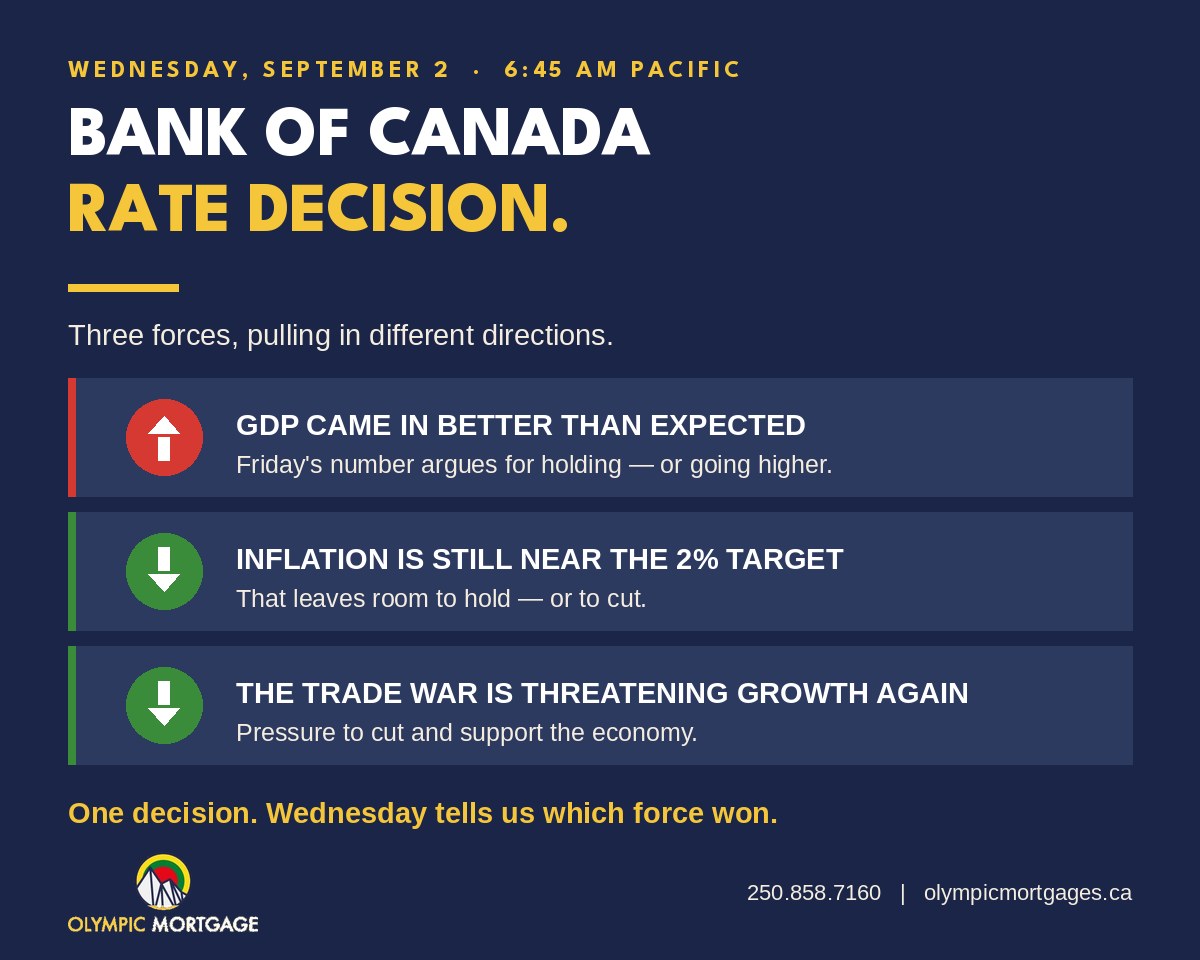
The Bank of Canada decides Wednesday, and the data is pulling both ways.
|
|
The announcement lands Wednesday, September 2. Going in, the case is genuinely mixed — three things are pushing in different directions at the same time.
Friday’s GDP number came in better than expected. A stronger economy is the argument for holding where we are, and if that strength keeps up, eventually the argument for going higher.
Inflation from the week before is still close to the 2% target. That is the argument on the other side. When inflation is sitting roughly where the Bank wants it, there is room to hold, and there is room to cut.
And the trade war is threatening our growth again. That is real downward pressure. Cutting is how the Bank supports an economy taking an external hit.
Anyone telling you confidently which way Wednesday goes is guessing. What is worth understanding is which of your rates this actually touches.
Variable rates move with the Bank of Canada. Fixed rates do not. Fixed pricing follows bond yields, and the bond market has already formed its own view. That is exactly why fixed money has been drifting up over the past few weeks while everybody stands around waiting on Wednesday — which brings us to what is still on the sheet.
|
|
|
|
Rate special · as of Friday, August 28
|
|
Fixed rates have moved up (in the short term). Here’s what’s still on the table.
|
|
Fixed pricing has been drifting up for a few weeks now. One lender still has a three-year fixed special sitting below where the rest of the market is quoting — and a special is not a rate sheet. It’s a tranche of money the lender has set aside at a sharp price. When that tranche fills, the rate is gone.
I expect it to last until the end of next week. That is an expectation, not a commitment. Nobody at the lender has given me a date, and specials get pulled early when the money moves faster than they planned for. There is no grandfathering either. If your file is not already submitted, you do not get the rate.
If you are buying, renewing or refinancing, get your application in. This is a 60 day rate special only. Preapprovals are not eligible, live deals only.
|
|
Current specials
|
| 4.04% |
3-year fixed · high ratio
Insured purchases and transfers
|
| 4.19% |
3-year fixed · conventional
Conventional purchases and refinances
|
| 3.60% |
5-year variable · insured
Insured purchases and transfers
|
| 3.90% |
5-year variable · conventional
Conventional purchases and refinances
|
|
|
Rates shown are as of August 28, 2026 and are subject to change or withdrawal without notice. On approved credit; not all applicants or properties will qualify. Insured (high-ratio) pricing requires the mortgage to qualify for default insurance, and restrictions apply including purchase price, amortization and property use. Conventional pricing applies where equity is 20% or more. Nothing here is an offer of credit or a commitment to lend. E.&O.E.
|
|
|
|
|
|
Olympic Mortgage Corporation
INSIDE A
LIVE FILE
What it actually looks like to work with me — a real client email, broken down line by line.
|
|
Most mortgage marketing tells you what a broker says they do.
I’d rather show you.
Below is a real email I sent to real clients — names, addresses, lenders and rates stripped out, everything else intact. They’re buying a new primary residence and pulling the down payment out of a rental they already own. Three properties in play, two of them without signed leases.
|
|
Move up and keep the rental. That’s one of our niches — I’ve helped around a thousand families do it.
It’s also getting harder every year. Prices are higher, so the equity you need is bigger. Regulations are tighter, so the qualifying math is less forgiving than it was even five years ago. The list of lenders willing to look at a borrower carrying three properties has shrunk — and the ones who will have gotten pickier about how the file is presented.
Which is exactly the argument for using someone who has built this file a thousand times. On a move-up, the strategy isn’t a nice-to-have. It’s the whole thing.
|
|
|
|
Here’s what that strategy looks like in practice.
|
|
|
|
Strategy 01
Structuring the purchase
|
|
“We’re applying for 80% on the subject purchase. Some of it can be fixed and some can be HELOC — you decide the split. Three-year fixed money is ‘on sale’ at one lender right now; everyone else’s three-year money is out to lunch. Five-year variable prices sharper at a different big bank, but there’s no HELOC available there. If you want long-term conventional variable, that’s the best route on rate.”
|
|
|
Three decisions, and they interact.
One — how much. 80% loan-to-value on the purchase, which is becoming the family’s primary residence. Conventional, no default insurance premium, maximum flexibility.
Two — the fixed / HELOC split. A HELOC revolves: pay it down, pull it back out, no penalty to break it. Fixed is cheaper but locked. Most people don’t need to pick one — they need a ratio. Someone with a renovation coming, or self-employment income that lands in lumps, should carry more HELOC. Someone who needs the payment nailed to the floor should carry more fixed. That’s a conversation, not a product.
Three — the lender is a consequence, not a starting point. One bank had a genuinely sharp three-year fixed and the rest of the market wasn’t close. A different bank had the best five-year variable — but no HELOC behind it. So the question was never “who has the best rate.” It was “which trade-off costs you less, given what you’re actually going to do with this property.”
Rates move weekly. What doesn’t move is knowing, on any given Tuesday, which lender is actually competitive and which one is quoting a number they have no real intention of winning with.
|
|
|
|
Strategy 02
Structuring the rental — the one that decides the deal
|
|
“We’re applying for 80% on the rental, but keep in mind the most you can carry in HELOC is 65%. If you’re in a fixed or closed variable and you sell before the term is up, there’s a penalty — so it may be better to take this as HELOC money. Rates on rentals price differently. If I can qualify this as a second home I will, but most likely we need to use rental income to qualify everything, which is exactly why I’m recommending HELOC. You can lock it in whenever you like.”
|
|
|
Before any of the mechanics, there’s a bigger question sitting underneath this one: how much do you borrow against the new primary residence, and how much against the rental? There are opposing forces at play. Primary residence rates are lower and qualify for the rate specials. But interest charged on a rental property is often deemed tax deductible, which can raise a client’s motivation to borrow more against the rental instead. (Always consult your accountant on that side of it.) Optimizing that mix is where I go deep, and it’s a conversation I have with each and every client.
Then the mechanics. Four things stacked into one paragraph:
The 65% ceiling is a rule, not a preference. You can borrow to 80% of value, but only 65% of it can sit in the revolving HELOC portion. The remaining 15% has to be a term mortgage. That’s regulation. No broker talks their way around it, and anyone who tells you otherwise is guessing.
Penalties are a consideration. A closed fixed mortgage usually garners a much higher penalty. Closed variable money is always a predictable three months’ interest, and HELOC money has no penalty at all. If there’s any real chance this property sells inside the term, paying a slightly higher rate to preserve the option to leave is often the cheaper decision overall.
Rentals price worse than primary residences. Sometimes. If a property can legitimately be qualified as a second home rather than a rental, the pricing improves, and I’ll always test that first. But there’s a trade: qualify it as a second home and the rent stops counting as income. On a file carrying this much property, they need that rental income to make the ratios work. So we take rental treatment on purpose, with our eyes open.
Don’t forget — you can lock in. A HELOC or a closed variable term can be locked into a closed fixed term without a penalty. Take the money as a HELOC now, and you can convert it to a fixed term later, whenever the rate suits you. You’re not re-qualifying and you’re not re-applying — you’re converting an approved facility on the lender’s standard conversion grid, at a time of your choosing rather than the calendar’s.
That’s not a trick. It’s just knowing how the machinery works, and setting the file up so the machinery works in your favour.
|
| |
|
|
A lot of brokers will tell you they “work with over fifty lenders.” Often what that means is they work with the ones that accept a file through a portal and never speak to a bank underwriter in their lives.
I’m the other kind. We are specialists with BMO, Scotiabank and TD, and we work extensively with the credit unions.
You don’t have to go from bank to bank. We’re a one-stop shop. And there’s no guessing with me either. No walking your credit bureau around town collecting inquiries while four people tell you four different things.
|
|
|
Of course we work with the non-bank monoline lenders too. First National, CMLS, MCAP and RFA all run strict guidelines, with less room for income exceptions or the one-off explanations a bank underwriter can accommodate. We use them often — usually when they have a rate special that can’t be ignored, or when a file simply fits their box better than it fits a bank’s. Knowing which of those is true before anything gets submitted is the same job as everything else on this page.
|
The line most people never see
|
|
|
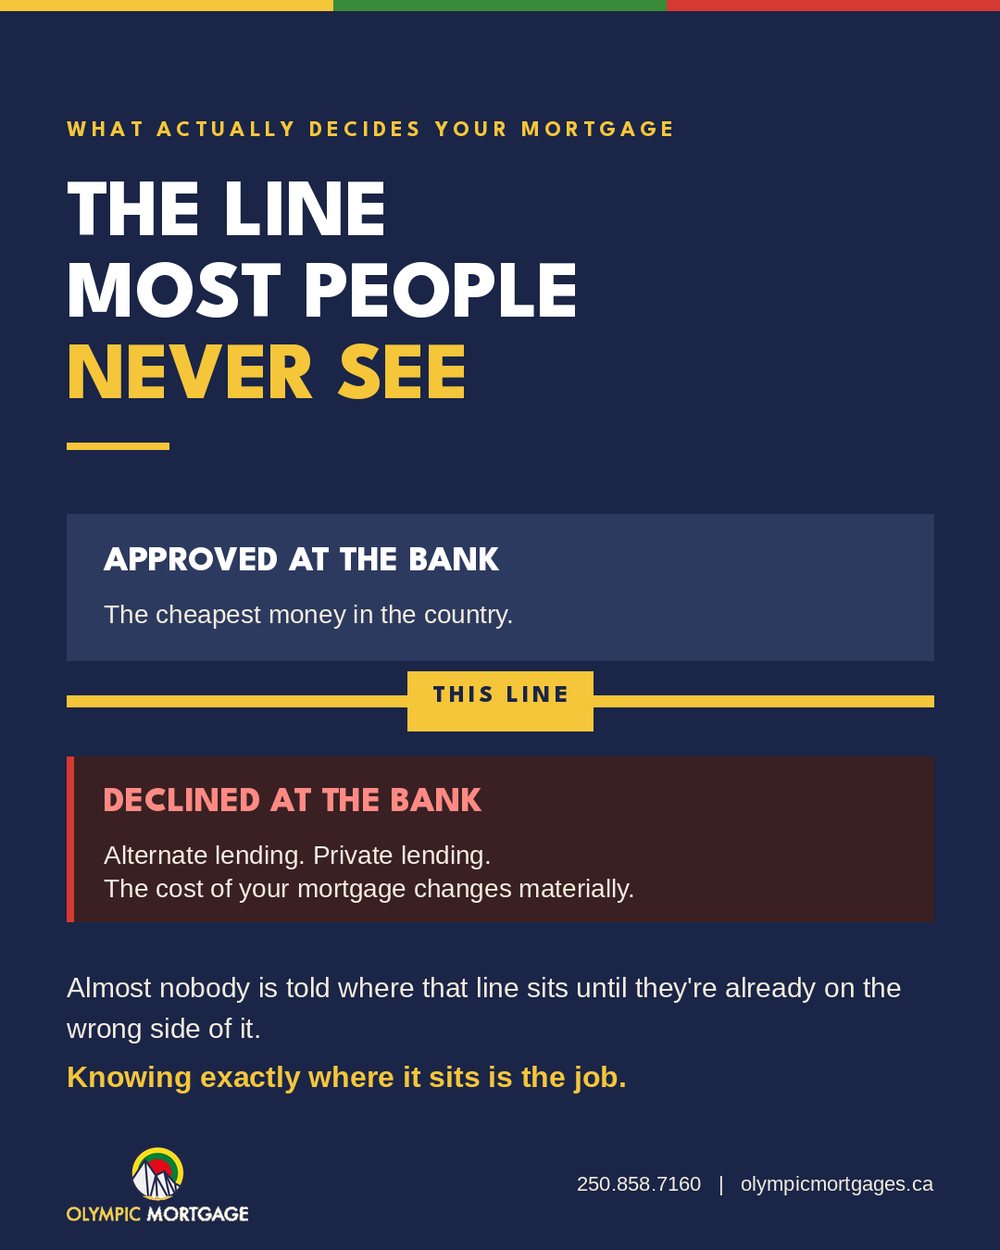
For most Canadians, the entire outcome of a financing turns on one invisible line.
On one side: the bank approves you, and you get the cheapest money in the country.
On the other: the bank declines you, you fall into alternate or private lending, and the cost of your mortgage changes materially.
Almost nobody is told where that line sits until they’re already on the wrong side of it.
That line is where I do my best work.
Because I am a bank specialist, your best chance at a bank approval is with me. I know how each of these lenders reads a file, and I put our best foot forward every time — the right lender, the right structure, the right supporting documents, presented the way that underwriter wants to see it. That is what gives my clients the best chance at getting approved.
It also means I know early when a file is not going to clear the bank. When that happens we stop wasting your time and go straight to the lender who will fund it. Not shotgunning your file across town hoping something sticks. One move, to the right place.
And once we’re on the alternate or private side, the job becomes finding you the cheapest and best-structured money available there — with the shortest possible path back to bank pricing. Alternate lending should be a bridge, not a destination.
|
|
Two kinds of bridges
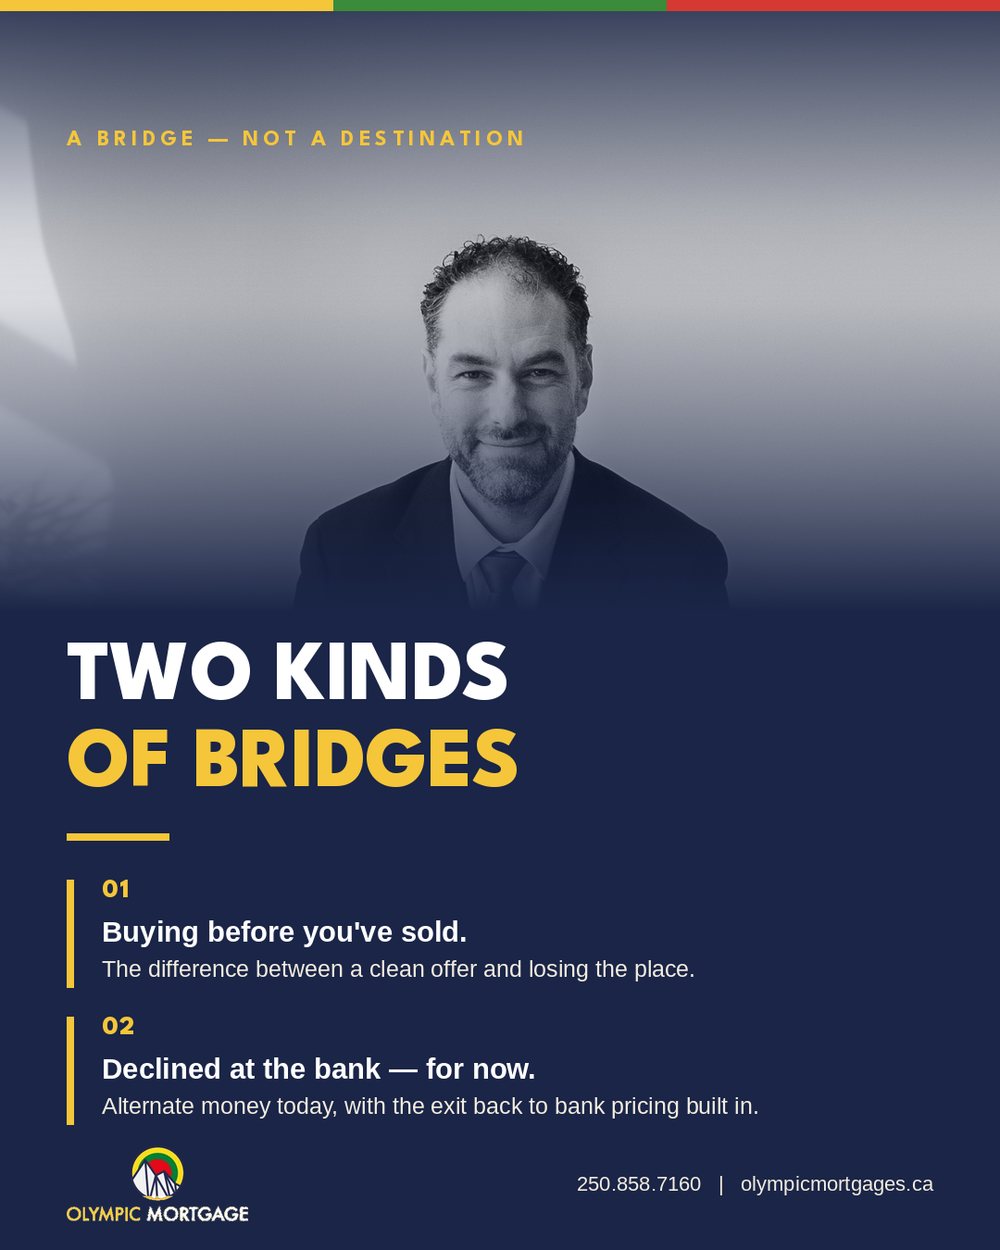
People hear “bridge financing” and think of one thing: covering the gap between buying a house and selling the old one. We do plenty of that, and it’s the difference between making a clean offer and losing the house you wanted.
But there’s a second bridge, and it’s the one that quietly matters more — the bridge between a bank decline and a bank approval.
Getting declined isn’t the end of the story. It’s the start of a two-year plan. Alternate money now, structured with the exit already in mind. Credit repaired, income seasoned, business-for-self history built out — whatever the actual blocker was. Then back to the bank at proper pricing.
Most people who end up in private lending stay there far longer than they need to, because nobody built them a way out. Building the way out is the entire point.
|
|
|
|
|
Execution
The unglamorous half
|
|
Strategy gets you the right structure at the right lender. Execution is what gets it funded. Back to that same email.
|
Documents, up front, in one batch
|
|
“A few points before my submissions: I need an updated consent — just reply all and confirm it’s fine for us to repull your bureaus. The lender will want updated paystubs, since the last ones are from April, and we should expect they may ask for an updated letter of employment. Your T4s from previous years are strong, so they may make an exception and waive the LOE.”
|
|
|
I’m telling them what the lender is going to ask for before the lender asks.
Bureaus have a shelf life. Paystubs have a shelf life. A file that was fully documented four months ago is a stale file today, and there is no version of this process where you get to skip that.
The line that matters is the last one. I’m not just listing documents — I’m telling them which one I think we can get waived, and why. Knowing which documents a particular lender will genuinely insist on, versus which ones they’ll flex on, is the difference between a five-day approval and a three-week grind.
Document requests that arrive in one batch at the start mean someone read your file. Document requests that trickle in over three weeks mean nobody did.
|
Your file, your way
|
|
“You can email the documents or upload them to the portal — I can drop the required fields in there for you. Let me know what you prefer.”
|
|
|
Small thing. Matters more than you’d think. We are flexible about how documents reach us — secure portal or email, whichever suits you — and we are quick about working them through the system once they arrive. The worst version of this process is the one where you’re fighting software instead of buying a house.
|
Where there are no leases
|
|
“The down payment will come from the refinance, but the lender will require mortgage statements on the two non-subject properties, plus leases. Where there are no leases, we’ll use economic market rents.”
|
|
|
Two of the rentals have no signed lease. That isn’t a dead end; it’s a technique. Most lenders will accept an appraiser’s opinion of economic market rent in place of a lease. And in a market where plenty of long-tenured tenants are paying well under market, market rent frequently qualifies you for more than the actual lease would.
Knowing that in advance is the difference between “we need leases, sorry” and “we’ll order the rent schedule with the appraisal.”
|
|
|
One more thing, since this is meant to be an honest look
|
|
There’s a line near the end of that email that I talk through with every single client:
|
|
“We will do our best to compete on the market, but please let me know if you are actively shopping anywhere else.”
|
|
|
I’m not asking for loyalty for its own sake. Lenders score brokers on how much of what we submit actually funds, and that score directly affects the pricing and the exceptions we can get — for you and for every other client on our desk. When the same file gets submitted by three different people, everybody’s score takes the hit, and the pricing gets worse for the next person in line.
So shop if you want. I’d just rather you tell me, so I can either beat it or tell you honestly that you’ve got a better deal than I can get. Both of those are useful answers.
|
|
|
|
|
|
|
|
|
Elsewhere
Thanks for having me back on the podcast
|
|
I sat down again with Adrian and Vince on the Victoria Real Estate Podcast, and it turned into one of the better conversations I’ve had about this market — what’s actually happening with pricing on the Island, where the qualifying math is biting people, and what buyers are getting wrong right now.
It’s worth an hour of your commute even if you’re not buying anything. They talk about Victoria specifically rather than national averages, which is most of the reason the national headlines feel so disconnected from what you see on the ground here.
Listen on Apple Podcasts, Spotify or Amazon Music — or straight from their site.
|
|
|
|
★★★★★
“I had an excellent experience with Roxan, Darla, David, and the entire Olympic Mortgage Team. From start to finish, they were professional, knowledgeable, customer-focused, and incredibly proactive.
They truly went above and beyond to find the best possible mortgage solution for my situation — they took the time to understand my needs, explored different options, and explained everything clearly… I always felt that they genuinely cared about getting the best outcome for me, rather than simply closing a deal.”
— Denis Starostin
Reviews are the best compliment we can get. If we’ve done a file for you and you’ve never left one, it genuinely helps — and if we got something wrong, I’d rather hear it from you directly than read it later.
|
|
If you’re planning a move
Moving up, refinancing to buy the next property, or already told no somewhere and not sure what that actually means — that’s the conversation.
David Steinberg, AMP, BComm
Owner & Lead Broker, Olympic Mortgage Corporation
250.858.7160 | olympicmortgages.ca
Plan the move. Manage the risk.
|
|
|
The client file described here has been genericized — names, property addresses, lender names and rates have been removed or altered. The rate specials shown above are current as of the date noted, are subject to change or withdrawal without notice, and are not a rate quote, a commitment, or an offer of credit. Every file is underwritten on its own merits, on approved credit.
Olympic Mortgage Corporation, Victoria BC | BCFSA #145716
|
|
|